

After two turbulent years defined by the collapse of the Yeezy partnership, inventory clean-ups, and a broader brand reset, Adidas has quietly engineered one of the most significant turnarounds in the modern sportswear industry.
At first glance, the recovery looks like a simple return to growth.
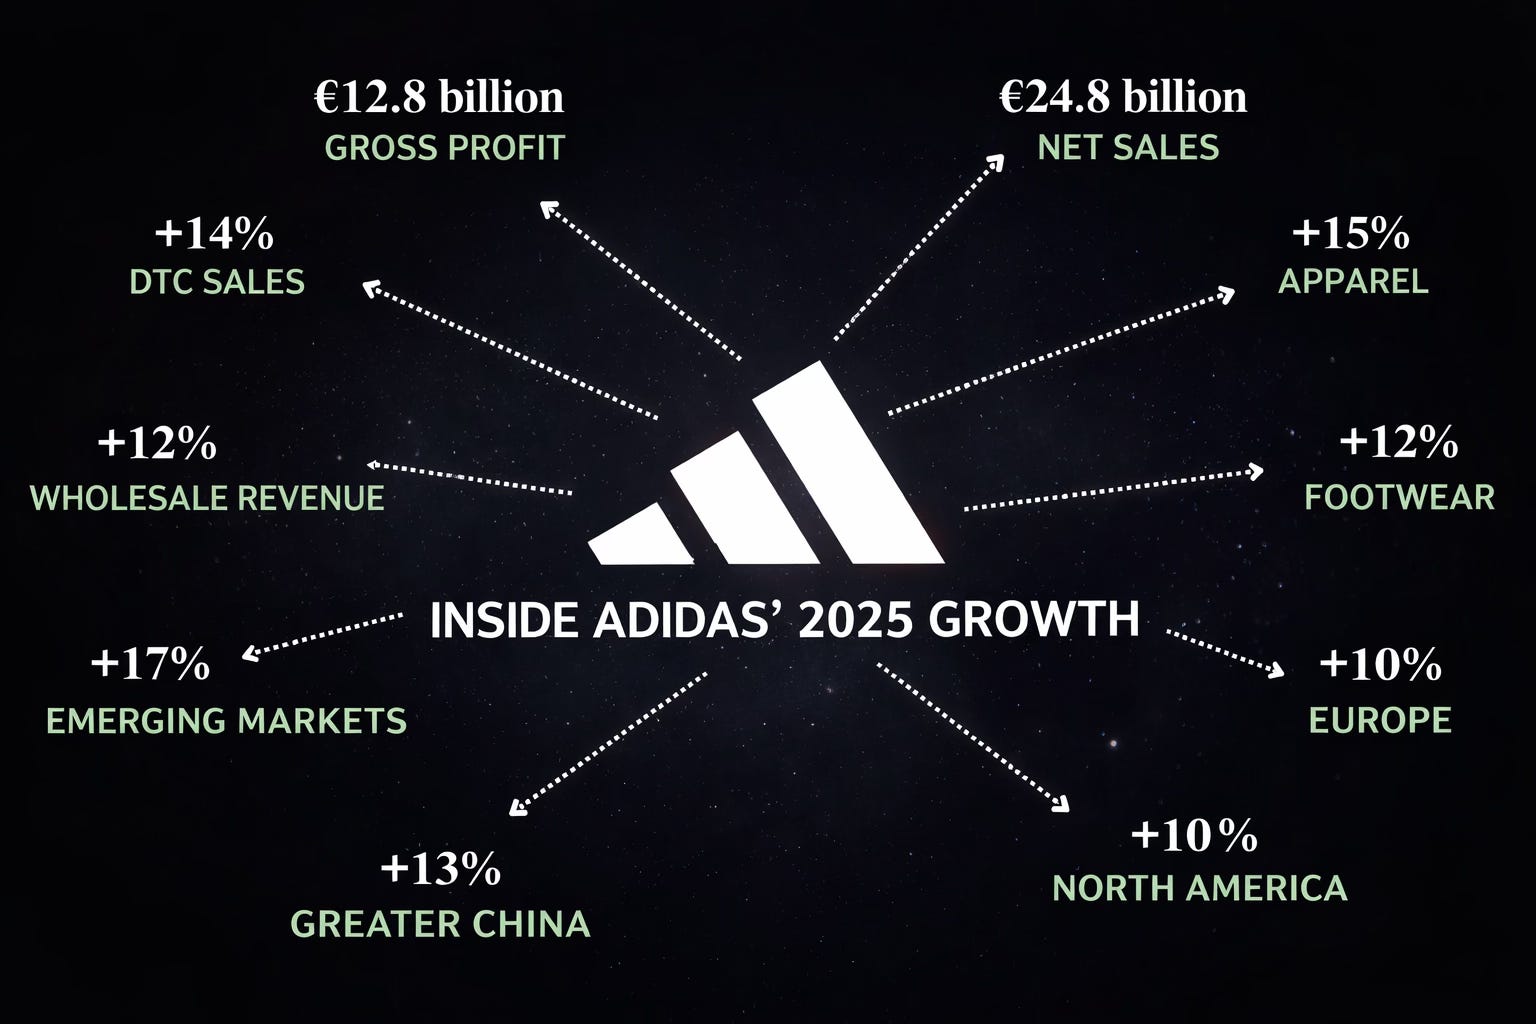
In 2025, adidas generated record net sales of €24.8 billion, up from €23.7 billion the year before. The adidas brand delivered 13% currency-neutral revenue growth for the second consecutive year.
But the headline number only tells part of the story. The real shift is structural.
Footwear, still the company’s largest economic engine, grew 12% currency-neutral. Apparel surged 15%, while accessories expanded 6%. Performance categories accelerated sharply, with Running alone growing more than 30%, largely driven by the global adoption of the Adizero platform. At the same time, lifestyle categories such as Originals and Sportswear continued to expand at double-digit rates.
Geographically, the recovery was unusually broad. Every major region posted double-digit currency-neutral growth from Europe and North America (+10%) to Greater China (+13%), Latin America (+22%), Emerging Markets (+17%), and Japan/South Korea (+14%).
The channel structure tells a similar story. Wholesale revenue grew 12%, while direct-to-consumer sales rose 14%, driven by 16% growth in e-commerce and 13% growth in owned retail.
And margins did improve. Gross profit increased to €12.8 billion, lifting gross margin to 51.6%, while operating profit jumped 54% to €2.06 billion. Net income rose 67% to €1.38 billion, and earnings per share climbed 76% to €7.46. What makes this even more notable is where adidas chose to invest.
Marketing spending increased 8% to €3.1 billion, even as operating expenses fell as a percentage of revenue.
The balance sheet tells a more nuanced story. Inventories rose 17% to €5.8 billion, reflecting the demands of accelerating growth, while adjusted net borrowings increased to €4.33 billion. Even so, leverage improved to 1.4× EBITDA, suggesting operating performance is strengthening faster than balance-sheet risk.
Capital allocation is now beginning to reflect that confidence. The company proposed a 40% dividend increase to €2.80 per share and signalled that shareholder returns could reach €1.5 billion through dividends and buybacks, with the board also authorising additional repurchases in the coming years if cash flow remains strong.
This report goes deeper into what sits behind these numbers - how adidas has been able to deliver this turnaround, and how its expanding network of sports partnerships is translating into real commercial demand.
If the headline numbers caught your attention, the story behind them is even more interesting, so make sure to read till the end….