

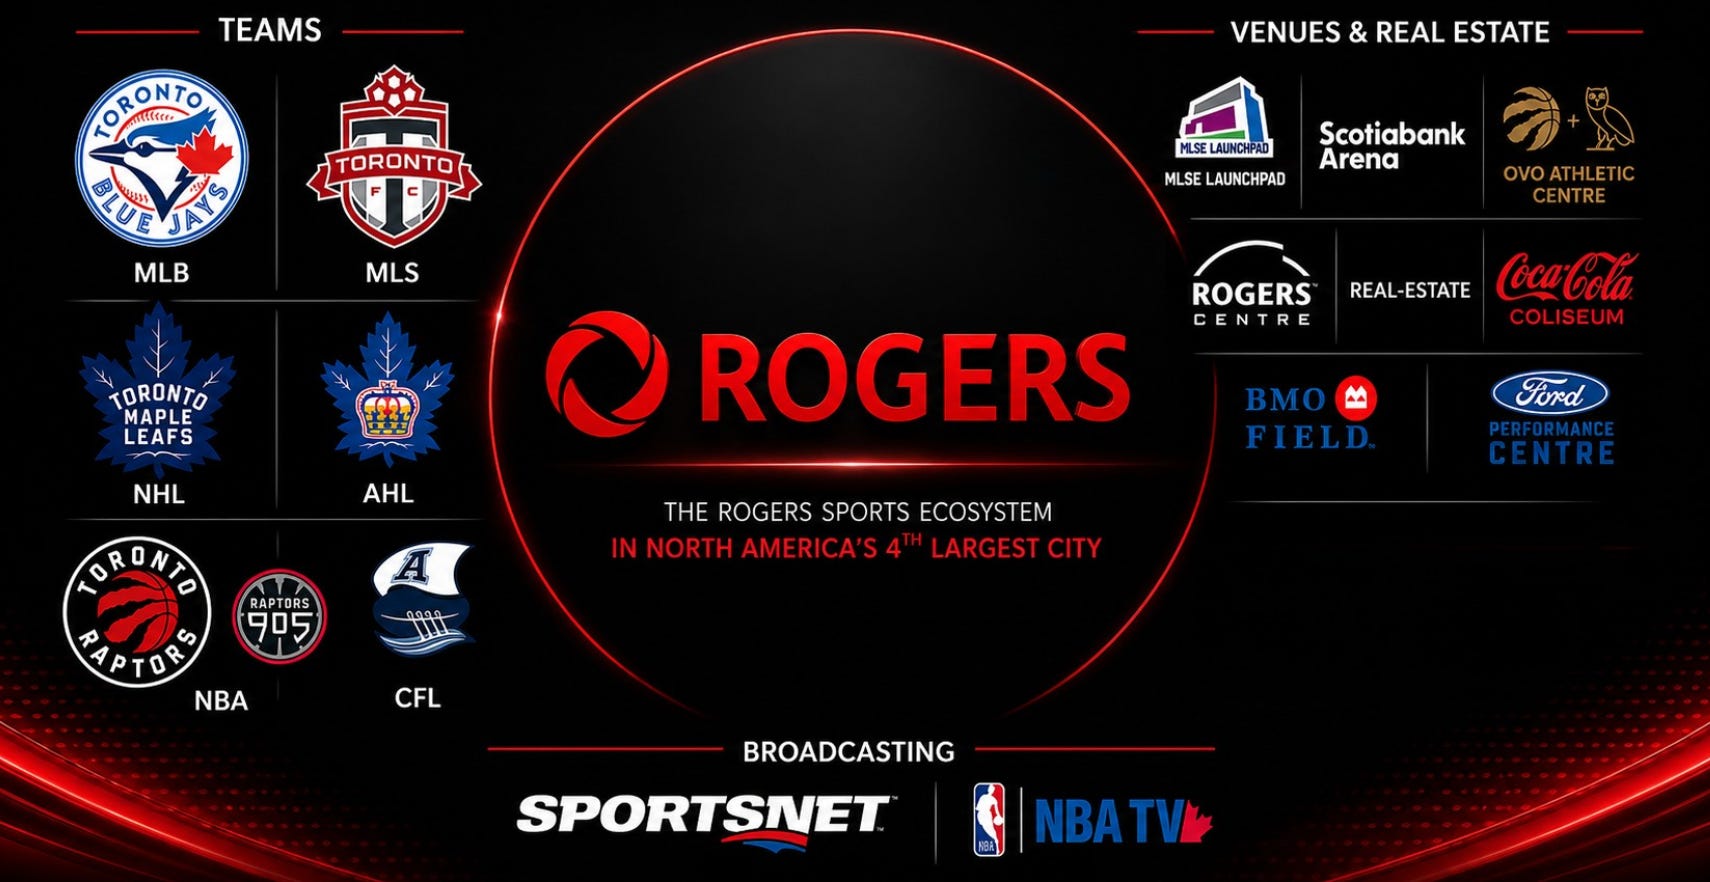
Rogers Communications is trying to pull off one of the biggest sports ownership restructures ever seen in North America. The company plans to group together some of its most valuable assets, including the Toronto Maple Leafs, Toronto Raptors, Toronto Blue Jays, Toronto FC, Sportsnet, and the Rogers Centre into one standalone business worth more than CAD $25 billion before selling a minority stake to outside investors.
Public markets often undervalue sports assets compared to private buyers. Teams have recently sold at huge numbers - the LA Lakers at around $10 billion, the Boston Celtics at roughly $6.1 billion, and minority stakes in NFL teams implying valuations of $8–9 billion. Rogers believes investors are not fully recognizing the value of the sports empire it already owns.
This is how the strategy is taking shape:
In 2024, Rogers agreed to buy BCE’s 37.5% stake in Maple Leaf Sports & Entertainment (MLSE) for CAD $4.7 billion, valuing MLSE at about CAD $12.5 billion. That deal officially closed in July 2025.
Rogers is expected to buy the remaining 25% stake from Larry Tanenbaum, likely valuing MLSE closer to CAD $16 billion.
After gaining full control, Rogers could sell a minority stake in the larger sports-and-media company to institutional investors. That would allow it to raise cash, reduce debt from the Shaw acquisition, and still keep control of the business.
Rogers is trying to separate its sports assets from its telecom business so investors can value them more clearly. Isolate premium holdings, give them their own identity, and unlock value the market may be missing.
If Rogers gets this right, it could unlock billions in value that the market may not fully recognize today, built around a rare combination of teams, venues, media, and distribution all concentrated in one city.
Inside how Rogers communication could build the most valuable sports ecosystem in North America….
Rogers CEO Tony Staffieri in a July 2025 interview with Sportico. He said Rogers gets “zero credit” in its stock price for already owning major sports assets.
What he meant is that investors value Rogers mostly as a telecom company, not as an owner of premium sports properties. Yet Rogers already controls assets like the Toronto Blue Jays, its stake in MLSE, and Sportsnet. Staffieri’s point was simple: the market is not fully recognizing how valuable those holdings are.
His argument is that by combining all of those assets into one dedicated sports and media company, Rogers can make that value more visible to shareholders.